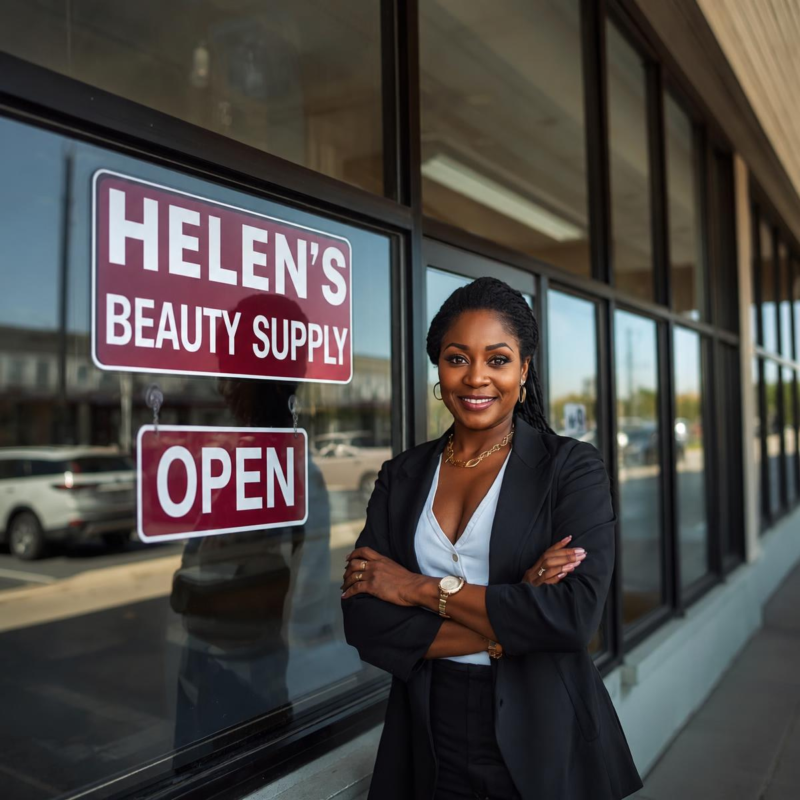
When I first came across this scenario, I did not know how I would present the case. At first glance, there is nothing unusual about Helen’s Beauty Supply. Helen has been a staple in the community for many years. The sign read Helen’s Beauty Supply and Hair Braiding. She worked in the business every day, she posted to social media regularly, and customers praised their work. Anyone would assume Helen owned the business that she operated everyday and she would benefit from its success.
To my surprise, that assumption would be wrong.
Once I identififed the business received SBA Funding, I was surprised to see although Helen performed the services that generated the revenue and built the customer base, Helen did not have beneficial ownership of the business entity that received the SBA funding. Someone else formed the business structure, had legal beneficial ownership of the entity, and successfully applied for and received $750,000 in SBA financing. Although Helen’s work created the value of the business, Helen was not the borrower of the loan and did not receive the proceeds.
This may sound like a lot of techinical business word salad: beneficial ownership, legal entity, business structure. The distinction may sound minor, but it reveals a few important lessons. One lesson is understanding how lenders evaluate funding opportunities and two is how this small business owner missed out on her own funding opportunity. She did not understand how wealth is often created through beneficial ownership not just by operating the business.
When the SBA loan was approved, the name on the building meant very little. What mattered was the business structure. The lender was evaluating the beneficial owner of the entity that submitted the application, the experience of the management behind that entity, and the evidence supporting the request. The lender was not underwriting Helen’s labor, customer relationships, or community reputation—those were not on the application. The application was strengthened by business experience, industry knowledge, and a track record that extended beyond the short history of the entity itself.
This perspective is worth taking a closer look into because it highlights a challenge many small business owners face more often than we are aware. Building a business operations and having beneficial ownership of the entity are not always the same thing. The individual performing the work is not always the individual controlling the structure, the assets, or the access to capital.
Helen built and operated a cash-flowing business, but the person who understood how lenders evaluate financing opportunities was positioned to benefit from the loan.
For small business owners, that may be the most important lesson in this story. Do not be satisfied with operating the business. Understand the importance of structuring the company for financing. Even if you are not ready at the time, you should always be preparing for financing. Becoming capital ready is not about getting a loan as soon as you begin operations. Helen was in business for many years, and the entity was only a few months old.
The lesson is not that an entity established within a few months can qualify for a large SBA loan. The lesson is that lenders often evaluate factors most business owners never consider. While Helen focused on running the business, someone else recognized the value that already existed and knew how to present that value in a way the lender could understand, verify, and finance.
Most small business owners were taught how to sell, market, and serve customers. Few were ever taught how lenders think and how they assess your business for financing.
The SBA Mastery Academy was created to close that gap. Inside the Academy, business owners learn how lenders evaluate opportunities, what SBA readiness actually looks like, and how to position their businesses before applying for funding.
Don’t wait until you need funding to learn what lenders are looking for.